
Short answer: Small business accountants help owners keep accurate books, file taxes, plan cash flow and make decisions. A CPA is a licensed US credential, while other accountants and bookkeepers can handle everyday records and tax preparation.
Hire help when payroll, sales tax, a loan, or growth makes your finances harder to manage. This guide covers costs, how to choose, and how AI and cloud tools are changing the work. It is general information, not tax or legal advice.
Table of Contents
Key Takeaways
- Small business accountants range from bookkeepers to CPAs, so they match the person to the job.
- Ask for a written scope and fee and compare fixed monthly fees with hourly rates.
- Cloud tools and AI speed up routine work, but people still review, advise and take responsibility.
- Do not upload sensitive bank statements to public AI tools without checking privacy terms.
- The best accountants explain things clearly and give advice, not just reports.
How We Prepared This Guide
We used IRS guidance for tax professionals and 2026 accounting resources, and we mark figures that come from summaries. Read our disclaimer and about page for how Henof works.
What changed in this update: we added CPA versus accountant guidance, costs, hiring questions, AI and data safety, accounting basics and a UK tax note, and we kept the earlier technology themes in updated form.
What Do Small Business Accountants Do?
Small business accountants keep financial records, prepare financial statements, handle tax filings and payroll support, and advise on budgets, pricing and growth. The right scope depends on your size and goals.
CPA vs Accountant vs Bookkeeper
| Role | Typical work | Good fit when |
| Bookkeeper | Records transactions and reconciles accounts | You need clean day-to-day books |
| Accountant | Statements, tax prep, planning and advice | You need reports and tax help |
| CPA | Licensed accountant who can sign certain audits and attestations | You need audits, complex tax or high-trust sign-off |
Paid tax return preparers in the US need a PTIN, as the IRS explains. A bookkeeper who does not prepare returns does not need one but cannot simply file taxes unless qualified.
When Should You Hire Small Business Accountants?
- When you register a business or choose an entity type.
- When you hire employees or run payroll.
- When sales tax, multiple states or inventory are involved.
- When you apply for a loan and need clean statements.
- When your books take too much time or contain errors.
If you plan to borrow, see how business bankers help small businesses.
How Much Do Small Business Accountants Cost?
Costs for small business accountants vary by location, scope and complexity, so there is no single price. Ask for a written fee for bookkeeping, tax returns and advice, and check what is billed extra.
Fixed monthly fees make budgeting easier, while hourly rates can suit occasional help. A CPA often costs more than a general accountant, but the right level depends on the work.
7 Ways to Choose Small Business Accountants
- Check credentials and licenses, such as CPA status, enrolled agent status or PTIN, as relevant.
- Look for experience with your industry and size.
- Ask which software they use and whether it fits yours.
- Get a written scope, fee and timeline.
- Test communication: do they explain things in plain language?
- Ask how they protect your data and who can access it.
- Check references and compare at least two options.
Questions to Ask Before You Hire
- What services are included in the fee?
- Who will work on my account, and how do we communicate?
- How do you handle deadlines and tax planning during the year?
- What happens if you make an error?
- How do you store and protect my financial data?
How Technology Is Changing Small Business Accountants
Automation
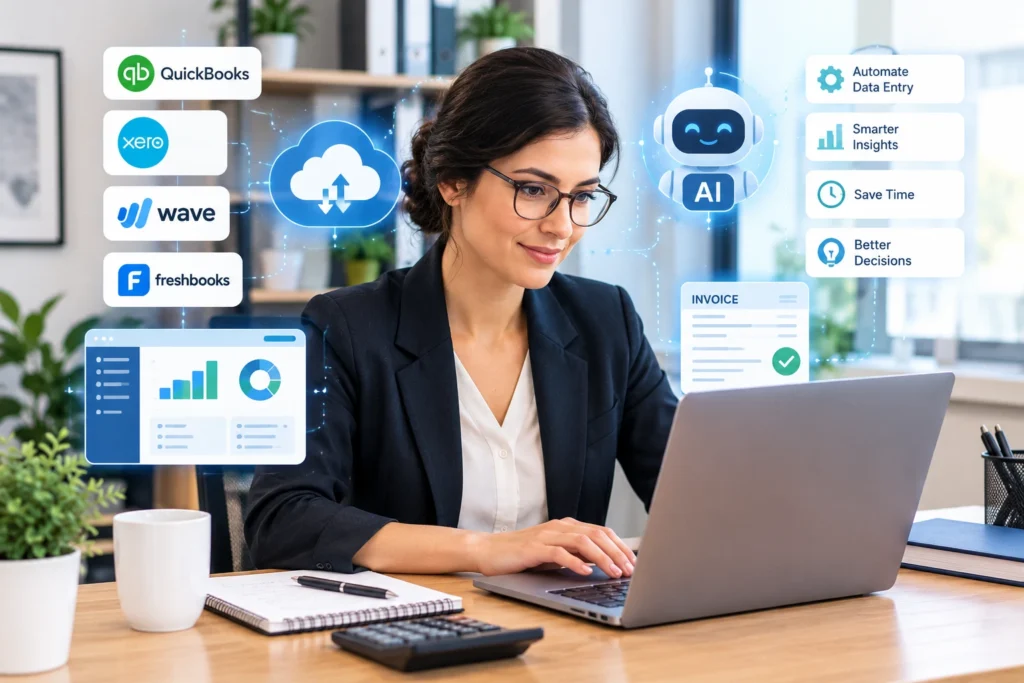
Software now automates data entry, invoice capture and reconciliation, which saves time and reduces some errors. That frees small business accountants to spend more time on analysis and advice. See our guide to business process automation software.
Cloud accounting
Cloud platforms let accountants and owners see the same numbers in real time, from anywhere. This supports faster decisions and easier collaboration, but you should still review permissions and backups.
Artificial intelligence
AI tools can summarize reports, draft categories and answer routine questions. They can make mistakes, so a person should review anything that affects tax, payroll or filings.
Be careful with sensitive files. Avoid putting bank statements into public AI tools unless you understand their privacy terms and read our guide to cybersecurity essentials.
Data analytics and advisory work
With cleaner data, accountants can turn numbers into advice on pricing, margins, cash flow and growth. Many clients now expect forecasts and planning, not only compliance.
Soft skills
As software handles routine work, clear communication and trust matter more. Good accountants explain complex numbers simply and listen to your goals.
Accounting Basics Every Owner Should Know
The five basic account types are assets, liabilities, equity, revenue and expenses. Common types of accounting include financial, managerial, cost, tax and audit work.
The Profit First method splits income into five accounts: income, profit, owner’s pay, tax and operating expenses. Valuing a business at about three times profit is only a rough rule of thumb, because multiples vary by industry and size.
A Note for UK Small Businesses
In the UK, look for chartered accountants, and check HMRC’s Making Tax Digital for Income Tax rules, which begin in phases from April 2026 for self-employed people and landlords above set income levels.
Is Becoming a CPA Still Worth It?
Industry commentary has described pressure on the profession, including workload and a smaller pipeline of new CPAs, which can affect availability and pricing. Demand for trusted advisors remains, so book early before busy seasons.
Small Business Accountants: Final Verdict
The best small business accountants combine accuracy, clear advice and good use of technology. Define what you need, compare two or three options, and protect your data.
For more guides, visit our business category and read about business accountant strategy.
About the Author
Shazain Mirha is a content writer covering finance and insurance at Henof. This guide is research-based and is not tax, legal or financial advice. Reviewed by Afaque Hussain, link building and outreach specialist.
Frequently Asked Questions
What is the difference between a CPA and an accountant?
In the US, a CPA is a licensed accountant who has met education, exam and experience requirements. Other accountants may handle bookkeeping, tax preparation and advice without that license.
What can a CPA do that a regular accountant can’t?
CPAs can sign audits and certain attestation work that only licensed CPAs may perform. For tax matters, CPAs, enrolled agents and attorneys can represent clients before the IRS.
At what point should I hire a CPA or accountant?
Consider hiring when you register a business, start hiring staff, face sales tax or payroll, plan a loan application, or find your books or taxes are taking time or causing errors.
How much should accounting cost for a small business?
It depends on scope, location and complexity. Ask for a written fee for bookkeeping, tax returns and advice, and compare fixed monthly fees with hourly rates.
Can I do my own accounting for my small business?
Yes, many owners do their own bookkeeping with accounting software. Get help with tax filings, payroll, entity choices and complex transactions, where mistakes can be costly.
Can ChatGPT do my bookkeeping?
AI tools can help explain terms, draft categories and summarize reports, but they are not a substitute for reviewed bookkeeping or tax advice. Always check outputs against your records.
Is it safe to put bank statements into ChatGPT?
Be careful. Avoid uploading sensitive statements to public AI tools unless you understand the privacy and data retention terms and remove account numbers and personal details first.
What are the five basic accounts in accounting?
The five basic account types are assets, liabilities, equity, revenue and expenses.
